
Research suggests those who use buy-now-pay-later services end up spending more
- Written by: Ashish Kumar, Senior Lecturer, RMIT University
Once, borrowing money to make a purchase was a relatively tedious process, not a spur-of-the-moment thing.
True, some stores offered lay-by plans that would let you pay for goods in instalments. But if they didn’t, and you didn’t already have a credit card, you’d have to go to a bank and apply for one.
That would mean providing a range of supporting documents, negotiating an appropriate credit limit, and waiting for approval. It’s unlikely you’d apply for credit just for a single, small purchase.
In recent years, though, the financial technology or “fintech” revolution in the customer credit market has changed all that, with the meteoric rise of buy-now-pay-later (BNPL) services.
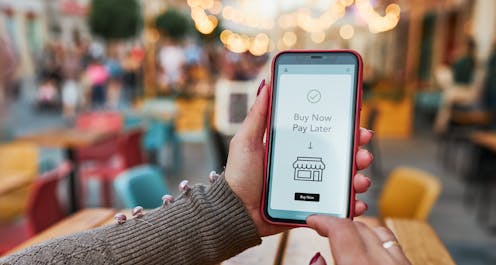
BNPL credit allows consumers to split their purchases into smaller, interest-free instalments. It is often directly integrated into online checkouts with fast approval, making it easy to purchase something instantly and spread the cost over coming months.
There are some obvious risks. Many BNPL providers charge less visible fees, such as late payment fees and account maintenance fees. In many countries, the BNPL sector is also less regulated than traditional credit.
But does it also change our spending habits? Our recent research uncovered a concerning insight: consumers who use BNPL services end up spending more money online than those who don’t. This effect is particularly strong among younger shoppers and those with lower incomes.
Our research
We analysed data from an online retailer in the Nordic region that offered customers three payment options for online purchases: card, pay on delivery and BNPL.
We found that consumers who used BNPL spent an average of 6.42% more than those who didn’t.
This increase was particularly noticeable for low-ticket items, suggesting that BNPL may encourage customers to buy more when shopping for smaller, everyday things.
Why might this be the case? For one, BPNL spending is constrained by the size of the loans on offer. In the US, the average BNPL loan amount is US$135 (A$217).
It may also be related to what’s known in economics as the “lipstick effect”, where customers under financial strain tend to reduce spending on big-ticket items in favour of lower-priced luxuries.
Selling such low-ticket items doesn’t always give online retailers the biggest profit margins. But it can play a crucial role in acquiring and retaining customers, and creating opportunities to upsell.
Our research also showed that younger, lower-income customers were more likely to spend more when using BNPL services, likely because it provides them with additional “liquidity” – access to cash.
Why might they be spending more?
It’s easy to see why so many consumers like BNPL. Some even think of it as more of a way of payment than a form of credit.
The core feature of such services - offering interest-free instalment payments for online purchases - has a significant psychological impact on customers.
It leverages the principle that the perceived benefit of spending in the present outweighs the displeasure associated with future payments.
This behaviour aligns with theories of “hyperbolic discounting” – our preference for smaller immediate rewards over larger later ones – and the related “present bias” phenomenon.
Our results also suggest customers with high category experience – that is, more familiar with the larger product categories carried by a retailer – and those more sensitive to deals and promotions are likely to spend more when online retailers provide BNPL as a payment option.
A growing influence on spending
The economic impact of BNPL is substantial in the countries that have pioneered its adoption.
In Australia, birthplace of Afterpay, Zip, Openpay, and Latitude, it’s estimated that (allowing for flow-on effects) BNPL services contributed A$14.3 billion to gross domestic product (GDP) in the 2021 financial year.
Industry research firm Juniper Research projects the number of BNPL users will exceed 670 million globally by 2028, an increase of more than 100% on current levels.
Substantial projected growth in the sector is attributed to multiple factors. These include increasing e-commerce usage, economic pressures, the flexibility of payment options and widespread adoption by merchants.
Buyer, beware
BNPL services can be a convenient way to pay for online purchases. But it’s important to use them responsibly.
That means understanding the potential risks and benefits to make your own informed decisions. Be mindful of your spending. Don’t let the allure of easy payments let you get carried away.
Customers should explore beyond the marketing tactics of interest-free split payments and pay close attention to terms and conditions, including any fees and penalties. They should treat BNPL like any other form of credit.
Whether you’re a shopper considering using BNPL or a business thinking about offering it, our research highlights that it may have the power to significantly influence spending patterns – for better or worse.
Authors: Ashish Kumar, Senior Lecturer, RMIT University