Modern Australian
The Times

How do banks assess you for a home loan? And how do you work out what you can afford?

  • Written by Ama Samarasinghe, Lecturer, Financial Planning and Tax, RMIT University
Streaming apps on a smart TV

Navigating the money side of buying a home can be daunting – especially if it’s your first time. Unless you’ve recently come into a small fortune, you’ll need to have saved a deposit and take out a home loan.

That means engaging with the world of banks and mortgage brokers, and grappling with what might be intimidating-sounding jargon – terms like “pre-approval”, “offset accounts” and “serviceability buffers”.

Here’s a general guide to some of the essential steps: how to figure out what you can afford, how the loan process works, and some key things to watch out for before taking the plunge.

How much can you afford?

Taking out a home loan means you’ll be required to make regular repayments over many years. So, a bank or other lender will first want to make sure you can afford them.

This article is part of The Conversation’s series on buying a first home. We’ve asked experts to unpack some of the biggest topics for first-home buyers to consider – from working out what’s affordable and beginning the search, to knowing your rights when inspecting a property and making an offer. It’s important to understand the difference between borrowing capacity and affordability. Your borrowing capacity is the amount a lender is willing to offer you, based on your income and debts, and their own stress tests. Affordability, on the other hand, is about you – your lifestyle, choices and actual spending patterns. These two things are related but don’t always align, so it’s important to factor affordability into your decision. Being clear on both helps you avoid taking on more debt than you can comfortably manage. Doing your own calculations first It’s a good idea to start with your own numbers. List all your household expenses over at least the past six months – everything from groceries to streaming subscriptions – and work out the monthly average. Streaming apps on a smart TV
Monthly subscriptions – such as streaming services – can have an impact on borrowing power. Oscar Nord/Unsplash

After setting aside some room for savings and unexpected costs, the remainder gives you an indication of what could be available for mortgage repayments.

As a rule of thumb, many suggest keeping repayments to no more than about 30% of your after-tax income.

Here are a few tips to avoid mortgage stress:

  • Budget for reality, not hope. Don’t assume you’ll slash spending just because you’ve bought a home.

  • Stress-test your budget. Could you still make the repayments if your interest rate rose by 0.25–0.5%? What if it rose by 1-2%?

  • Don’t forget the extra costs that come up with home ownership. Factor in insurance, council rates and higher utility bills in a larger home.

How much will the bank lend you?

Your borrowing power depends mainly on:

  • household income
  • living expenses and debts (credit cards, car loans, buy-now-pay-later arrangements)
  • number of financial dependants.

Most banks have online calculators in their banking apps to check your borrowing capacity. The Australian Securities and Investments Commission (ASIC)’s Moneysmart site also provides calculators for borrowing and repayments.

Lenders are also required by law to check a borrower could still afford repayments if interest rates rose by a certain amount. This “serviceability buffer” is currently three percentage points.

Pre-approval doesn’t guarantee a loan

Getting pre-approval means a lender has reviewed your finances and indicates they’re willing, in principle, to lend you up to a certain amount.

But it isn’t a binding contract. You’re not locked into taking the loan, and the lender isn’t legally bound to provide it.

Still, getting pre-approval can have some benefits, including:

  • giving you confidence about your borrowing capacity
  • helping set realistic price limits and narrowing a property search
  • signalling to real estate agents and sellers that you’re a serious buyer, which can make you more competitive in a hot market.

At auctions, pre-approval is especially important. Once the hammer falls, the sale is binding – there’s no cooling-off period and no finance clause.

If you don’t have pre-approval in place, you could win the bid but may be unable to secure finance, leaving you at risk of losing your deposit.

A gavel is held by an auctioneer
If financing falls through after winning an auction, it could mean losing a deposit. Mick Tsikas/AAP

Different types of loan

One of the first decisions you’ll face is whether to go with a principal and interest loan or an interest-only loan.

Principal and interest is the standard choice. Each repayment reduces both your loan balance and the interest owed. Most first-home buyers opt for this option because it steadily pays down the debt.

Interest-only loans mean that for an agreed period (say five years), you only cover the interest. Repayments are lower during that time, but the loan balance itself doesn’t shrink.

To illustrate, if you took out a $200,000 interest-only loan at 5% for five years, you’d pay $10,000 a year in interest. But at the end of the five years, you would still owe the full $200,000.

Interest-only loans can make sense for some investors focused on cash flow, but they’re far less common for first-home buyers.

Finding a loan

There are many ways to find a loan that suits your needs. You can compare products directly with lenders, use comparison sites, or go through a mortgage broker.

Mortgage brokers compare loans on your behalf and are often paid a commission by the lender, meaning you aren’t directly charged a fee.

It’s important to make sure they’re licensed (check ASIC’s professional register), reputable, and – if possible – recommended by family or friends.

A good broker will break down fees, features and hidden costs so you’re comparing more than just the interest rate. Before you sit down with a broker, think about what matters most to you: getting the lowest cost loan, or flexibility through features?

Take offset accounts as an example, where savings can reduce interest on the loan. An offset is a transaction account linked to your loan. If you owe $450,000 but keep $30,000 in the offset, you’ll only pay interest on $420,000.

Another common feature is called a redraw facility. This lets you make extra repayments (thus reducing the amount of interest you pay) and withdraw them later if needed.

Disclaimer: This article provides general information only and does not take into account your personal objectives, financial situation, or needs. It is not intended as financial advice. All investments carry risk.

Authors: Ama Samarasinghe, Lecturer, Financial Planning and Tax, RMIT University

Read more https://theconversation.com/how-do-banks-assess-you-for-a-home-loan-and-how-do-you-work-out-what-you-can-afford-266389

The Number on a Roller Blind Fabric That Nobody Explains

Somewhere in the fabric book, next to the colour name, there is a percentage. Three per cent. Five per cent. Ten per cent. Nobody explains it, most c...

What’s Trending in Men’s Jewellery This Father’s Day!

Finding a Father’s Day gift that feels personal, stylish and genuinely wearable is not always easy. While socks and novelty mugs have traditionall...

Road Signs: Understanding Their Role in Clear and Effective Signage

Effective signage and display hardware can help businesses communicate information, promote products and organise customer or visitor movement. Road...

Bottle Label Printing: Key Factors to Consider Before Your Next Packaging Run

Effective packaging begins with understanding the product, bottle material, artwork and production requirements when planning bottle label printing. H...

Planning a Long-Distance Move With Interstate Movers Melbourne

Moving between states involves more planning than a typical local relocation. Along with packing and transporting household belongings, you need to...

Understanding the Role of an I/O Controller in Industrial Automation

Modern industrial systems depend on accurate communication between sensors, machines and control systems. An I/O controller can help manage this commu...

How the Right Mining Hose Supports Demanding Operations

Mining environments place considerable demands on equipment used for material transfer, water management and processing. Hoses operating in these co...

Simple Ideas for Making Social Gatherings More Memorable

We have all been to those parties where everyone just stands around the kitchen island, staring at their phones, waiting for someone else to make a mo...

Outdoor Wall Lights: Improving Exterior Lighting Around Your Home

Lighting can influence how a room looks, feels and functions, so the right fitting should be selected according to both appearance and practical req...

Commercial Office Cleaning: Combining Routine Office Cleaning With Melbourne Service

Keeping a workplace clean requires a service that can accommodate everyday tasks as well as the particular needs of the business. Professional comme...

Caravan Sales in Queensland: How to Find the Right Caravan for Sale QLD

Caravan ownership is about more than having somewhere to sleep while travelling. For many Queenslanders, it is one of the best ways to explore regio...

What Sir Walter Buffalo Turf Actually Costs in 2026 (And Why Quotes Vary So Much)

Two quotes landed on a Hills District homeowner's kitchen table last spring for the exact same 80-square-metre backyard. One said $12 a metre. The o...

Nearly 1,300 NSW Hospital Beds Are Occupied By People Who Are Ready To Go Home

1,276 people in NSW hospitals have been medically cleared for discharge but remain in hospital because they're still waiting for NDIS or aged care sup...

National Survey Launched to Measure Operational Impacts of Federal NDIS Policy Reforms

The effects of recent NDIS reforms are beginning to move beyond policy papers and into day to day service delivery. A new national survey is asking ...

Beyond the Nappy Cake: Baby Shower Gifts That Get Used

What new Australian parents unwrap, keep, and quietly thank you for months later. Six weeks after my daughter was born, I did an audit of the baby sh...

Parent-Advocates Are Reshaping Frontline Disability Service Delivery

Parents have always been part of the disability sector. They advocate, coordinate services, challenge decisions and often become the person holding ev...

Vista Cruises Enters "Two-Flagship Era" as Vista Aurora Completes Inaugural Voyage

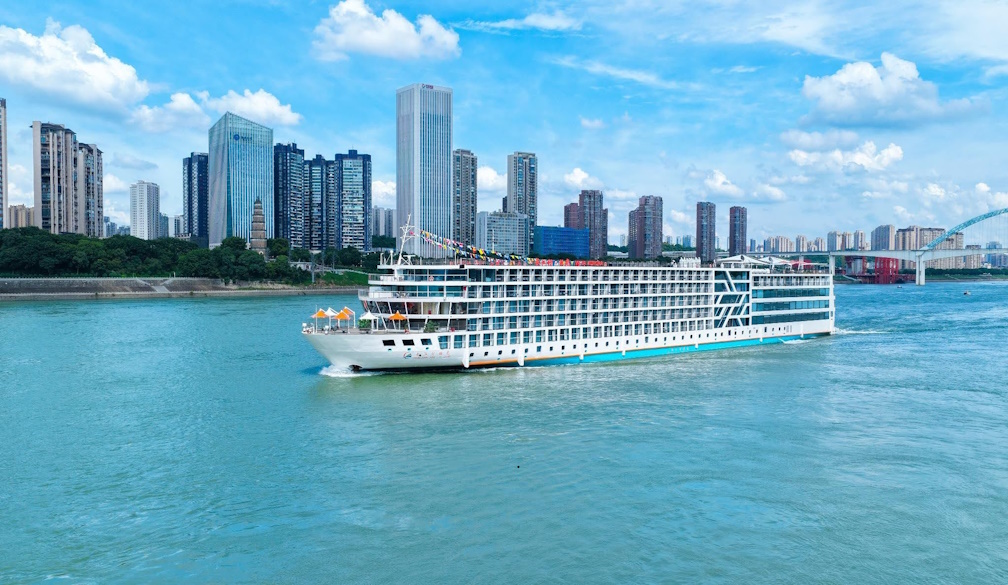
Vista Aurora Sets Sail along the Yangtze. (Photo courtesy of the company)YICHANG, China — August 5, 2026 — Vista Aurora, a high-end interprovinc...

A Digital Preparation Checklist For International Medical Conferences

An international medical conference compresses many responsibilities into a few days. A delegate may need to present research, move between venues, ...