
Google AI


Modern Australian

I’m close to retirement age. What are my options for drawing on my super savings?

  • Written by: Di Johnson, Senior Lecturer, Finance and Financial Planning, Griffith University

Retiring well means making a series of decisions to ensure a financially secure post-work life. One practical step is to work out the income you need each week to survive and thrive when you stop working.

If you are one of the many Australians still working and growing your super, knowing more about tailored retirement income products might help to plan.

There are two main ways to use super savings in retirement:

  • through products that provide an income stream, and/or
  • through lump sums.
I’m close to retirement age. What are my options for drawing on my super savings?
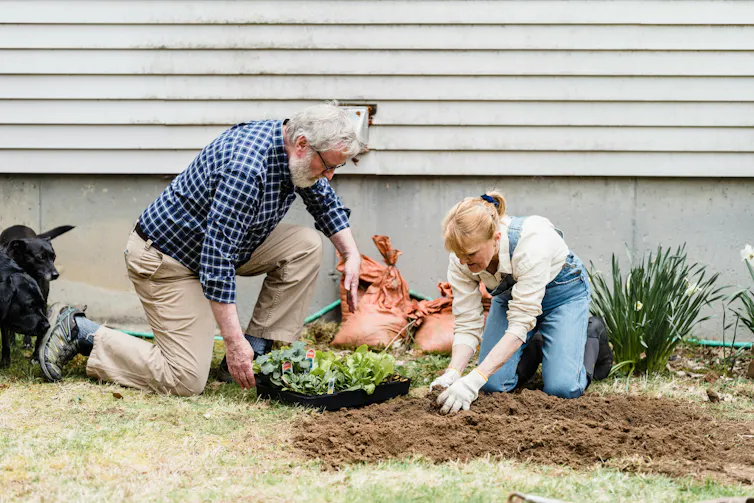
CC BY-NC It’s easy to put off thinking about superannuation when retirement is years away. In this five-part series, we ask top experts to explain how to sort your super in a few simple steps, avoid greenwashing, and set goals for retirement. Account-based pensions The most common product for a retirement income stream in super is an account-based pension. These can be set up outside super, but there are advantages inside super. Around 80% of retired super fund members have one or more account-based pensions in super. These products offer flexibility, control and continued exposure to investment markets. They allow retirees to convert part, or all, of their super balance into an income stream while keeping an allocated sum invested. More than one can be set up, at different times, and with different investment choices, so your investment balance keeps growing while providing income in the short-term. Retirees can choose how much they withdraw, as long as they meet the government’s minimum withdrawal requirements. Arguably, the greatest advantage of an account-based pension within super is its tax effectiveness compared to investments outside super. Once a super member is fully retired, both the investment earnings and income drawn from an account-based pension in super is tax-free. One of the disadvantages of account-based pensions in super is that the age-based minimum drawdown rates might not suit your investment timing or income preferences. Investment returns are not guaranteed, and you don’t know how many years of income will be needed. If you die before the funds are fully drawn, however, your beneficiary can receive the remaining money. An older couple doing gardening
One or more retirement products can provide steady income for retirees. Greta Hoffman, Pexels

Another option for regular income: annuities

Retirees can also use their super to buy another type of income product called an annuity. There are a few main types of annuities and you can choose if you want the income payments:

  • guaranteed over a fixed period of time
  • investment-linked over a fixed period or for life, or
  • guaranteed for the rest of your life, typically adjusted for inflation.

The cost of the annuity will vary depending on these factors. Annuities provide more certainty both in the payments and timeframe for income, regardless of investment market performance.

In Australia, fewer than 5% of super member accounts are annuities. But that may be changing, as more retirees realise the advantages of including an annuity in their super income planning.

Annuities can be bought using super or non-super money, but using super has the advantage of tax-free earnings and income.

In addition, for age pension eligibility, Centrelink only takes into consideration 60% of the value of a lifetime annuity compared to 100% of an account-based pension. This favourable treatment means your super savings can last longer, because your retirement income will be supplemented with more age pension.

On the downside, annuities have less flexibility. Once you have committed a lump sum of super to purchase the annuity, you cannot convert that back into a lump sum.

The income from annuity returns may also not be as high as in an account-based pension, because there is a trade-off between investment returns and guaranteed income.

Choosing the right mix for your circumstances

Retirees may benefit from a retirement income strategy that includes a combination of account-based pensions and annuities, depending on their personal needs and circumstances.

Once aged 67, retirees will also be eligible for the age pension, within asset or income limits. More than 60% of retirees receive at least some age pension, around 40% as their main income.

There is a maximum amount that can be transferred to pension phase within super, regardless of whether you choose an account-based pension or annuity, or a combination. That cap currently sits at A$2 million.

What about lump sums?

Once a super fund member reaches preservation age, usually age 60, and ceases at least one job, they may be able to access some or all their super as a lump sum. Alternatively, a member can access some or all their super as a lump sum when they turn 65, regardless of their employment.

With more people heading into retirement with mortgages, lump sums can be used to pay down debt, or for home repairs, holidays or even gifting.

How the lump sum is used may affect your age pension. In 2025, the average lump sum taken out by newly retired members was around $58,000.

While income stream products have a range of advantages within super, taking at least some super as a lump sum is common, even later in retirement. More than $71 billion was paid out in lump sums from superannuation in 2025 across 2.26 million member accounts.

Advice can help

Getting advice on coordinating super income streams and age pension entitlements can make a big difference to maximising your income while managing risk. Licensed financial advisers are in high demand, either within or outside your super fund.

Super funds can provide a range of valuable information, calculators and support. Other online tools are also available that can help with retirement income planning, including taking age pension eligibility into account.

Disclaimer: This article provides general information only and is not intended as financial advice.

Authors: Di Johnson, Senior Lecturer, Finance and Financial Planning, Griffith University

Read more https://theconversation.com/im-close-to-retirement-age-what-are-my-options-for-drawing-on-my-super-savings-276377

Breach of Contract in Business: What Are Your Options?

Contracts are essential to business relationships. They establish expectations, allocate responsibilities and provide a framework for delivering goods...

How Pest Control Companies Can Rank for the Problems Customers Search First

Introduction SEO for Pest Control needs to start with the customer’s problem. Most people do not search for pest services in a neat or technical wa...

What Are the Benefits of Renovating an Older Home in Sydney?

Sydney has plenty of character homes, from Federation cottages to mid-century brick homes. Renovating rather than rebuilding can preserve what makes t...

Pool and Deck Design: How to Plan the Perfect Outdoor Living Space for Your Sydney Home

For many Australians, the backyard is where life happens. Summer barbecues, weekend swims and long evenings outdoors are all part of the lifestyle, ...

Is Solar Pool Heating Worth It? What Sydney Homeowners Should Know

There's nothing quite like a backyard pool on a hot Sydney day. But once autumn rolls in, many pools sit unused for months because the water is simp...

Planning a Luxury House Move: A Week-by-Week Timeline for Prestige Sydney Homes

Selling or buying a prestige home is a major milestone. Whether it's a waterfront residence in Birchgrove, a grand Federation home in Haberfield or ...

Downsizing or Upgrading Your Caravan? Here's How to Sell It Without the Hassle

Selling a caravan can feel like a major task, especially when you are unsure about its value, paperwork, or how to find a buyer. Whether you are dow...

The Best Overseas Adventure Holidays for Australians Who Love the Outdoors

Australia offers no shortage of incredible outdoor experiences, but sometimes the best way to satisfy your sense of adventure is to head overseas. A...

Cape Town Wine Shuttle: Winelands Tasting & Tours

Embark on an unforgettable journey through the picturesque Cape Winelands, where world-class wines and breathtaking scenery await. Our Cape Town Win...

Metal Fabrication: Choosing Metal Fabrication Melbourne Services for Custom Projects

What Modern Metal Fabrication Involves From individual components to complete structures, metal fabrication brings together processes such as desig...

Why Giant Rats Tail Grass Keeps Coming Back After Spraying

Giant Rats Tail Grass (GRT) is one of the most frustrating pasture weeds for farmers and lifestyle property owners. You spray an infested area, see th...

When Custom Cardboard Boxes Make Sense for Your Business

Custom cardboard boxes can be useful when a standard carton does not fit a product, packing method or presentation requirement particularly well. A ...

Full-Height vs. Pop-Top Caravan: Which Is Better for Family Travel across WA?

A pop-top caravan is an excellent choice for travellers who want the comfort of a caravan without committing to a larger, bulkier setup. With a lowe...

Bottle Label Printing: Key Factors for a Professional Finish

Why the Printing Method Matters When businesses need packaging or printed containers developed for a particular application, the right supplier can m...

Virtual Livestock Fencing and GPS Tracking: Improving Visibility Across Cattle Properties

What Virtual Livestock Fencing Means for Modern Cattle Management Managing cattle across extensive properties requires more than knowing where anim...

Sydney Pawnbrokers Explained: How Hocking Your Car Actually Works

Sometimes you need cash, and you need it soon. If you own a car, you may already have a way to get it. That's what people mean when they say they've...

Moving Interstate from the Gold Coast to Brisbane (or Back)? What Removalists Wish You Knew First

Have you talked to anyone who’s done the move? They say the same thing: the drive up the M1 is the easy part. It's everything around it that catches...

Why the Spring School Holidays Are a Great Time to Visit Coffs Harbour

The spring school holidays are a good time to spend a few days on the Coffs Coast. The weather is starting to warm up, there is plenty to do outdoor...