
Google AI


Modern Australian

Labor's 2% cap on private health insurance premium rises won't fix affordability

  • Written by: Peter Sivey, Associate Professor, School of Economics, Finance and Marketing, RMIT University
This week, Opposition Leader Bill Shorten announced a new private health insurance policy the Labor Party will take to the next election. First, Labor will get the Productivity Commission to conduct a full review of the private health insurance system. Second, and more controversially, Shorten promised a short-term 2% cap on premium increases for two years.

The promised cap is in response to consistently high premium increases of around 5% in recent years. In justifying the policy, Shorten said:

… the idea these big insurers are making record profits and yet the premiums keep going up and up, it can’t be sustained.

This announcement has already been greeted with scepticism and fury from the health insurance industry, with industry body Private Healthcare Australia branding the proposal “disastrous”.

Read more: INFOGRAPHIC: A snapshot of private health insurance in Australia

As the proposal explicitly targets their profit margins, their response is predictable. However, in this case, they are right to complain. The premium cap policy is a crude measure that is unlikely to improve long-term affordability and may further distort the market in the short term.

Unintended consequences

Price controls introduced by governments usually have good intentions, but often have unintended consequences.

Consider, for example, the proposal to introduce caps on rent increases in the United Kingdom. Rent controls are among the most well-understood policies in economics: they reduce the quality and quantity of housing, leaving renters facing long search times to find housing and poorly maintained properties.
Labor's 2% cap on private health insurance premium rises won't fix affordability

Private health insurers drop their cover for certain treatments and procedures to save money. Look for a therapist near me.

In health insurance, the most likely immediate response to the cap would be for insurers to increase the amount of exclusions – procedures and treatments that aren’t funded – and co-payments associated with policies. 

So, while prices are kept low by the cap, consumers are effectively getting less coverage for their money. This would enable insurers to maintain their profit margins, but produce no gain, and further confusion, for consumers.

We already know the number of policies with exclusions, such as hip replacements and childbirth, has grown substantially. Labor’s proposal will probably accelerate the trend.

Read more: Confused about your private health insurance coverage? You're not alone

Long-term pain

Alternatively, as this proposed cap is time-limited, insurers may just put up with the pain of lower margins for a couple of years, with the timeline too short for significant changes to exclusions.

However, there may still be negative long-term impacts. We can look back in history for a clue about the long-term effects of a temporary cap on premiums. In 2000 and 2001, the Howard government implemented an effective “freeze” on private health insurance premium increases.

As can be seen in the graph, average premium increases were below 2% in 2000 (the largest insurer, Medibank Private, had a 0% increase in 2000), and were zero in 2001.
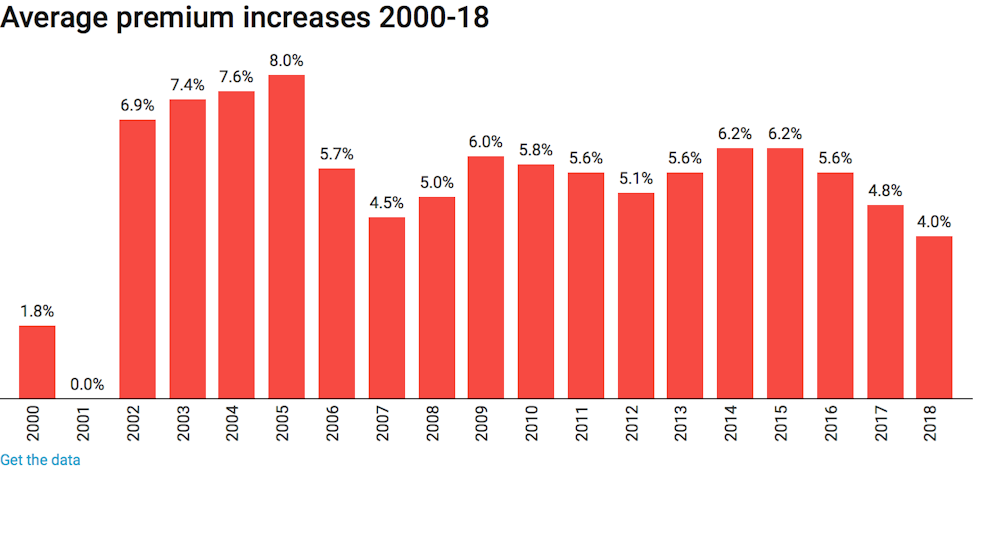
Labor's 2% cap on private health insurance premium rises won't fix affordability Average private health insurance premium increases in Australia from 2000 to 2018. Author

While consumers in 2000 and 2001 may have gained from lower real-terms premiums, we can see the long-term effects in the years from 2002 to 2005, when premium increases were between 7 and 8%. This is clearly an attempt by health insurance companies to “catch up” on the increases they missed in 2000 and 2001.

So, we may expect history to repeat itself if Labor wins the next election and introduces this policy: premiums will just rise faster in the years following the cap, negating any short-term benefit to consumers.

Why costs are rising

The proposed Productivity Commission review is much more promising in tackling important issues in the market, including lack of competition, confusing exclusions in policies, and its interaction with public funding through Medicare and public hospitals.

However, there is no solution to premium rises way in excess of general inflation if recent trends in healthcare technology and use continue. The number of hospital visits funded by private health insurance is growing strongly, at an average of 5.5% per year over the past five years.

Read more: Here's what's actually driving up health insurance premiums (hint: it's not young people dropping off)

Growth is across all areas of health care, from elective surgery like cataracts (4.9% a year) and hip replacement (5.5% a year) to diagnostic procedures such as endoscopy (4.4% a year) and life-saving cancer treatments like chemotherapy (5.5% a year).

We are paying more for our health insurance because we are using it more. No crude, short-term measures to restrict premium growth will deal with this fact. And good luck to the Productivity Commission in trying to reverse a global trend for higher private health care expenditure.

Authors: Peter Sivey, Associate Professor, School of Economics, Finance and Marketing, RMIT University
Read more http://theconversation.com/labors-2-cap-on-private-health-insurance-premium-rises-wont-fix-affordability-91232

Breach of Contract in Business: What Are Your Options?

Contracts are essential to business relationships. They establish expectations, allocate responsibilities and provide a framework for delivering goods...

How Pest Control Companies Can Rank for the Problems Customers Search First

Introduction SEO for Pest Control needs to start with the customer’s problem. Most people do not search for pest services in a neat or technical wa...

What Are the Benefits of Renovating an Older Home in Sydney?

Sydney has plenty of character homes, from Federation cottages to mid-century brick homes. Renovating rather than rebuilding can preserve what makes t...

Pool and Deck Design: How to Plan the Perfect Outdoor Living Space for Your Sydney Home

For many Australians, the backyard is where life happens. Summer barbecues, weekend swims and long evenings outdoors are all part of the lifestyle, ...

Is Solar Pool Heating Worth It? What Sydney Homeowners Should Know

There's nothing quite like a backyard pool on a hot Sydney day. But once autumn rolls in, many pools sit unused for months because the water is simp...

Planning a Luxury House Move: A Week-by-Week Timeline for Prestige Sydney Homes

Selling or buying a prestige home is a major milestone. Whether it's a waterfront residence in Birchgrove, a grand Federation home in Haberfield or ...

Downsizing or Upgrading Your Caravan? Here's How to Sell It Without the Hassle

Selling a caravan can feel like a major task, especially when you are unsure about its value, paperwork, or how to find a buyer. Whether you are dow...

The Best Overseas Adventure Holidays for Australians Who Love the Outdoors

Australia offers no shortage of incredible outdoor experiences, but sometimes the best way to satisfy your sense of adventure is to head overseas. A...

Cape Town Wine Shuttle: Winelands Tasting & Tours

Embark on an unforgettable journey through the picturesque Cape Winelands, where world-class wines and breathtaking scenery await. Our Cape Town Win...

Metal Fabrication: Choosing Metal Fabrication Melbourne Services for Custom Projects

What Modern Metal Fabrication Involves From individual components to complete structures, metal fabrication brings together processes such as desig...

Why Giant Rats Tail Grass Keeps Coming Back After Spraying

Giant Rats Tail Grass (GRT) is one of the most frustrating pasture weeds for farmers and lifestyle property owners. You spray an infested area, see th...

When Custom Cardboard Boxes Make Sense for Your Business

Custom cardboard boxes can be useful when a standard carton does not fit a product, packing method or presentation requirement particularly well. A ...

Full-Height vs. Pop-Top Caravan: Which Is Better for Family Travel across WA?

A pop-top caravan is an excellent choice for travellers who want the comfort of a caravan without committing to a larger, bulkier setup. With a lowe...

Bottle Label Printing: Key Factors for a Professional Finish

Why the Printing Method Matters When businesses need packaging or printed containers developed for a particular application, the right supplier can m...

Virtual Livestock Fencing and GPS Tracking: Improving Visibility Across Cattle Properties

What Virtual Livestock Fencing Means for Modern Cattle Management Managing cattle across extensive properties requires more than knowing where anim...

Sydney Pawnbrokers Explained: How Hocking Your Car Actually Works

Sometimes you need cash, and you need it soon. If you own a car, you may already have a way to get it. That's what people mean when they say they've...

Moving Interstate from the Gold Coast to Brisbane (or Back)? What Removalists Wish You Knew First

Have you talked to anyone who’s done the move? They say the same thing: the drive up the M1 is the easy part. It's everything around it that catches...

Why the Spring School Holidays Are a Great Time to Visit Coffs Harbour

The spring school holidays are a good time to spend a few days on the Coffs Coast. The weather is starting to warm up, there is plenty to do outdoor...