
Banning contactless and credit card surcharges won’t help – open banking reform is what’s needed
- Written by: Alexandra Andhov, Chair in Law and Technology, University of Auckland, Waipapa Taumata Rau
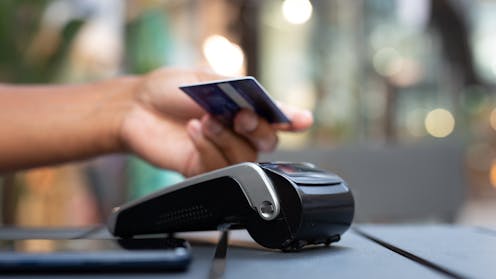
We’ve all been there – absentmindedly tapping a credit or debit card to pay for something at a shop, only to remember moments later there is a 2.99% surcharge.
These surcharges are extra fees added to the total when a shopper opts for credit card and contactless payment rather than swiping and entering a PIN with a debit card.
Typically, they amount to only a dollar or two per transaction, but such sums add up. Collectively, surcharges cost New Zealanders around NZ$150 million a year.
So it was unsurprising the government’s announcement to ban them was met with widespread approval.
Many welcomed it as a cost-saving measure and a return to hassle-free payments. Even the incumbent payment duopoly, Visa and Mastercard, backed the move.
But don’t break out the champagne just yet. The situation is more complex than it appears and, without further reform, the policy risks several unintended consequences, particularly for small businesses.
A short history of surcharges
Surcharges are typically used by businesses to recoup the fees Visa and Mastercard charge to process online and contactless transactions.
These are not a single fee but a bundle of charges across the payments chain, levied by banks. The calculation of these fees is opaque and has long been criticised. Though each fee may seem negligible, the aggregate cost is significant.
Mastercard recently settled a £200 million class-action lawsuit in the United Kingdom after it was alleged that anti-competitive practices in fee setting led to higher retail prices. The settlement, approved by the Competition Appeal Tribunal, covered 44 million consumers.
Similarly, New Zealand’s proposed reform addresses the symptom, not the cause. Consumers may no longer see the 2.99% surcharge, but the cost won’t have vanished – it will merely be hidden.
Unable to pass processing fees directly to card users, businesses will instead embed them in their prices. Whether one pays by cash, conventional or contactless cards, the bill will still be higher – just less transparently.
As in the UK Mastercard case, inflated merchant fees will be passed on in the form of higher prices, even for those not using cards.
Banning surcharges alone does little to improve transparency. Indeed, it may worsen matters, encouraging more consumers to tap and pay – thereby increasing the volume of costly card transactions.
The role of open banking
The European Union banned card surcharges nearly a decade ago – but in 2018 it also introduced the revised Payment Services Directive (PSD2), updating EU rules put in place in 2007. The second directive opened the door to cheaper, more innovative alternatives.
At the heart of PSD2 is “open banking”, which compels banks to let customers share account data with third-party providers – with the customer’s consent.
Instead of entering card details on a website when shopping online, a consumer selects “pay with your bank”, logs in securely via their banking provider, and authorises the transaction. Funds move directly from the customer’s account to the merchant, bypassing card networks altogether.
In the Netherlands, the iDEAL system connects consumers directly with their banks and charges interchange fees (fees paid for transactions between banks) below 0.2%. As a result, Dutch shoppers don’t need to maintain credit card subscriptions to buy online.
Spain’s Bizum – a collaborative platform developed by local banks – now boasts over 20 million users and processes more than 600 million transactions annually.
Sweden’s Swish shows that even smaller countries can innovate. It offers a free service to private users, while businesses pay only 1–3 kronor (roughly NZ$0.15). This is a fraction of what Visa or Mastercard charges.
Europe’s blueprint for reform
Europe’s success did not happen by chance. PSD2 created a regulatory framework that encouraged innovation and competition. It required banks to open their systems, introduced strong consumer protections, and mandated fee transparency.
Crucially, it did not merely ban surcharges – it enabled alternatives.
New Zealand has begun this journey. The Customer and Product Data Act, which takes full effect in December, lays the foundation for open banking. But much more is needed to implement it effectively and unlock the potential seen in Europe.
The Reserve Bank of Australia recently consulted on payment regulation. It proposed not only abolishing surcharges but also capping interchange fees at 0.3% for credit cards (down from 0.8%) and reducing debit-card fees to just six cents per transaction.
Such reforms directly benefit small businesses and, according to the Reserve Bank’s consultation paper, could save Australians around A$1.2 billion in interchange fees.
Seizing the moment
While the open banking foundation has been laid, the government must encourage further innovation and support the development of local financial technology firms. New Zealand could follow the Australian and European examples in several ways by:
mandating full fee disclosure from card networks
capping interchange fees
introducing strong customer authentication standards to protect data and build trust
encouraging the adoption of alternative payments through business education and incentives.
Europe’s approach has proven effective in reducing costs for everyone. Firms in the UK using open banking, for example, spend 8% less annually on payment processing.
More dramatically, when organisations fully replace card payments with direct bank transfers, cost reductions can be substantial. The UK government estimates savings of 70–80% for public sector organisations switching from debit cards to open banking payments.
Imagine a New Zealand where banks and financial technology firms build a real-time payments network that costs a fraction of existing systems. Such a move could reshape the payments landscape.
Alternatively, the sector can wait and watch as customer-focused firms offer better solutions, while those clinging to opaque fees and outdated models risk being sidelined.
Authors: Alexandra Andhov, Chair in Law and Technology, University of Auckland, Waipapa Taumata Rau